Click on charts to enlarge, courtesy of SEB.


 As historical evidence shows, debts make all dreams come true.As historical evidence shows, debts make all dreams come true.
While the outlook for the Nordic economies is still fine ...
The economic recovery continued in Q2, with GDP growing quarter-on-quarter for the second consecutive quarter. The pick-up in GDP has so far been fairly modest, but the cycle seems to have bottomed. Exports have so far been the main driver of the recovery, as expected, with Latvia benefiting from the recovery in the other EU countries as well as Russia. The domestic economy is seen improving in the second half of the year, although consumption is likely to remain weak due to the still elevated unemployment, the tight credit markets and the weak income development.Click on charts to enlarge, courtesy of Nordea Markets.
Nevertheless, the improving consumer confidence indicates that domestic demand is on the recovery track as well. We see the economy returning to year-on-year growth in 2011 on improving exports and strengthening consumption, with growth gaining further momentum in 2012. However, it will take years for the economy to reach the levels seen a couple years back.
 Just pray that global slowdown is not hitting the export dependant Latvia again.
... GREED & fear is not an economist and is not going to get into a discussion about whether this will prove to be a “double dip” US or just a severe loss of economic momentum. This is partly a question of semantics. The critical point from a market standpoint is that the bond action is giving a strong message that nominal GDP growth is slowing in the US, and it is clear from the Japanese experience since 1990 that stock markets trade around swings in nominal GDP growth in a deflationary environment.

July proved to be a horrible month for the US housing market as the expiration of the homebuyer’s tax credit deeply impacted transaction volumes. For the second day in a row we saw terrible US housing numbers as yesterday’s new home sales report extended the very poor existing home sales data released on Tuesday. New home sales fell by -12.4% to 276k units in July, a record low since the data series started in January 1963...
Interestingly the two housing reports actually marked the low point for risk on both days. The S&P 500 was -1.14% post yesterday's data but recovered steadily throughout the day to close +0.33% higher. The data was brushed aside by the homebuilders for the second day (+3.73% in the session). Indeed the sector has gained +7.2% since the release of Tuesday’s existing home sales data. There does seem to be a belief that July will mark a bottom in activity given that it was the first post tax credit month. Whilst this may be true we suspect that there has been a psychological shift against housing amongst US consumers...
Given the weakness in data yesterday, which included a very weak underlying Durable goods orders report, we have to admit that the resilient of equities markets was somewhat surprising. Is the data getting so bad that QE2 is now more likely than it was 48 hours ago? ...
So far the equity market has shrugged off much of the weaker data that abounds, and has not joined the bond market in a perceptive move. The equity market will though crumble like the house of cards it is, when the nationwide manufacturing ISM slides below 50 into recession territory in coming months. Indeed the new orders data for August, already reported in regional ISM's suggests the equity market is going to get some sentiment crushing data in the very near term. ...
 Now, when bad data are increasing the likelihood of QE2, JPY is weakening for the second day on speculation Japan to intervene, and the resilience of markets in face of really bad data does suggest a short squeeze before a rude shock?
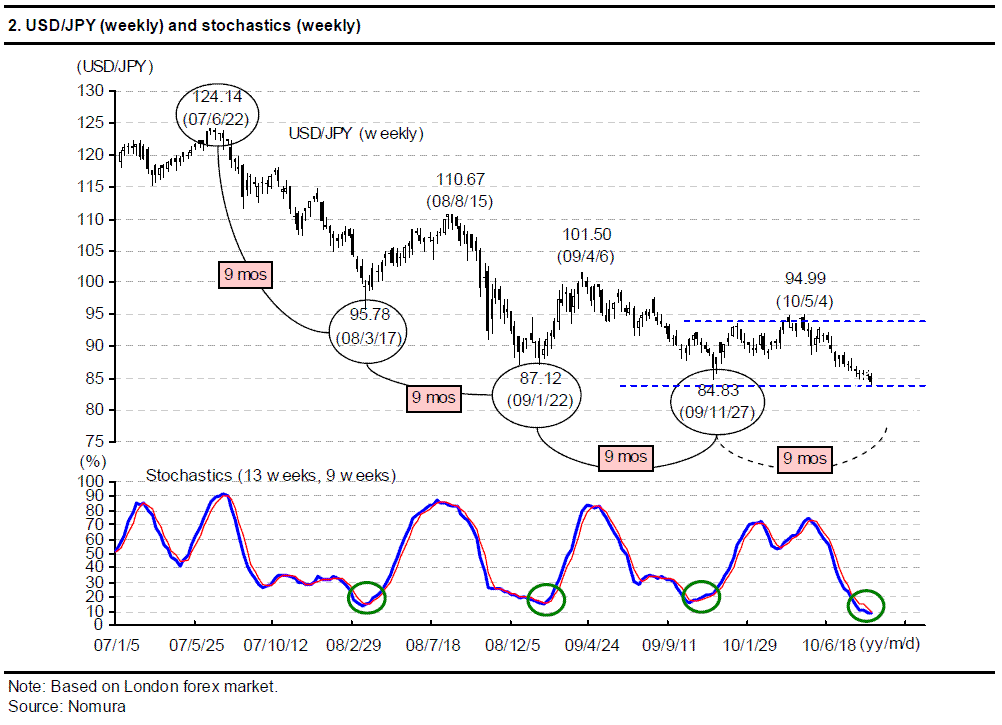
Risk assets will probably rally if the Fed pumps more liquidity into the system, but the stock and corporate bond markets may riot before the Fed acts. Thus, the risk/reward balance has become too unfavorable to maintain a pro-growth investment stance in our view.Is this the capitulation of rational bulls? There are, of course, other types of bulls too. In the meantime it becomes widely accepted that Japanese Yen makes some problems for the "risk-on trade". Is this due to inter-market correlations?


In light of recent developments we are revising our view of the magnitude and shape of the US economic recovery.
...The inventory cycle has apparently had only a modest positive follow through impact on growth which now threatens to slow to the sluggish pace of final demand as the inventory cycle is largely played out. In this sense the recovery has not so much lost momentum, as it never really had solid underpinnings.


